-
 Man City whistleblower Pinto to stay under police protection
-
BMW pulls car lease offer from German far-right politician
-
 US leads fresh Ukraine peace push with Miami talks
-
Brazil election offers Jair Bolsonaro a shot at revenge
-
 Verstappen continues resurgence with pole for Singapore sprint
-
Man Utd boss Carrick 'personally' affected by Man City verdict
-
 Cuban ration book, symbol of the revolution, gathers dust
-
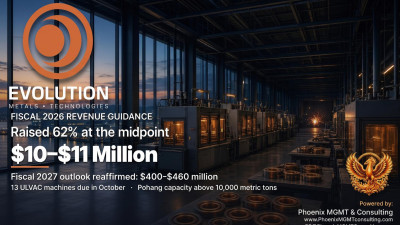
Evolution Metals & Technologies Corp. Raises Fiscal 2026 Revenue Guidance 62% at Midpoint to $10–$11 Million and Reaffirms $400–$460 Million Fiscal 2027 Outlook
-
 Stocks advance, oil retreats as Trump rules out pre-vote Iran attack
-
Red Bull's Verstappen takes pole position for Singapore GP sprint race
-
 Man City case causing 'uncertainty' for whole Premier League, says Iraola
-
Chelsea star Palmer 'committed' to England insists Alonso
-
 Talks with Iran can only succeed without threats, president says
-
OpenAI denies firing researchers over AI safety warnings
-
 Home hope Zheng sets up Mertens clash in China Open semis
-
Turkey warns opposition, press over investment fund crisis
-
 Lombardia promises gripping end to season in Pogacar absence
-
Hurricane Isaias now major storm as it heads to US Gulf Coast
-
 Barca skipper Raphinha out against Getafe and Galatasaray
-
Djokovic crashes out of Shanghai Masters in his first match
-
 MEXC and Payward Highlight Collaboration as Crypto and TradFi Converge at TOKEN2049
-
EU says Turkey's crackdown on rights hampers membership bid
-
 EU states agree beefed-up European financial markets watchdog
-
Two Renoir paintings stolen in France recovered: mayor
-
 Eritrea, Ethiopia trade barbs as Tigray rebels retreat
-
German leader outraged at Schroeder birthday visit to Putin
-
 Kompany 'proud' of Man City success despite guilty verdict
-
Stocks up, oil retreats as Trump rules out pre-vote Iran attack
-
 Man City will win appeal over financial charges, says Maresca
-
South African judge Navi Pillay wins Nobel Peace Prize
-
 Fernandez logs record lap at Indonesia MotoGP practice
-
'I completely trust the club,' says Man City boss Maresca
-
 Navi Pillay: S.Africa's global rights activist and Nobel winner
-
'10 out of 10' Quintana reminisces over dream Vuelta win
-
 Ufunded Launches “Spotlight” Series, Documenting the Minds Shaping Modern Trading
-
Maddinson given shock recall but fails to score
-
 Russell goes fastest in practice for smoggy Singapore GP
-
Navi Pillay, South African rights champion, wins Nobel Peace Prize
-
 For exiled Russian director Zvyagintsev, triumph without belonging
-
Saudi Arabia says three killed at airport as Yemen war expands
-
 Home hope Zheng storms into China Open semi-finals
-
Everton's US owners mull sale of club two years after takeover
-
 Zverev churns out win in Shanghai Masters opener
-
Ukraine takes Russia fight to 'scorching sands' of Sahel
-
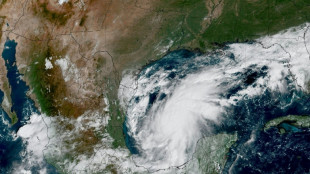 Hurricane Isaias strengthens en route to US Gulf Coast
-
Chinese AI tool pulled to prevent 'misuse' after South Korea hacks
-
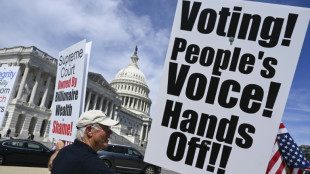 US activists deploy poll volunteers over Trump intimidation fears
-
Asian stocks mostly up as traders weigh AI, oil dips after surge
-
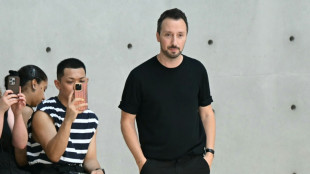 Saint Laurent designer Vaccarello leaves after glittering decade
-
Walking through flames: orangutans rescued in Indonesia fires
France's debt spiral Crisis
France’s economic outlook at the start of 2026 is bleaker than at any time in recent memory. After years of debt‑fuelled budgets and incremental reforms, the eurozone’s second‑largest economy finds itself mired in a crisis of slow growth, skyrocketing debt and political gridlock. Public borrowing now exceeds €3.3 trillion—roughly 114 percent of national output—and official projections suggest the ratio will climb past 118 percent by 2026 and could breach 120 percent by the end of the decade. Investors and policymakers increasingly fear that, without a radical shift, France may be on course for a painful financial reckoning.
A debt mountain and soaring interest costs
Successive governments have promised to rein in spending, yet the deficit remains the highest in the euro area. In 2024 the gap between revenues and expenditures reached almost 6 percent of GDP, and by mid‑2025 it still hovered around 5.4 percent—nearly double the European Union’s 3 percent ceiling. Hopes of reducing the shortfall to below 5 percent in 2026 were dashed in December 2025 when parliament failed to agree a budget, forcing ministers to roll over the previous year’s spending. The emergency finance law allows the state to collect taxes and issue debt from 1 January 2026 but contains no savings measures, prompting warnings that the deficit could exceed 5 percent yet again.
These chronic deficits have propelled debt to alarming heights and swollen the cost of servicing it. Audit officials warn that annual interest payments, already more than €59 billion in 2026, will reach €100 billion before the decade is out—making debt service the largest single budget item. Economists estimate that interest outlays could rise from about 2 percent of GDP today to close to 4 percent in the early 2030s, squeezing resources for education, healthcare and infrastructure. The prospect of higher global interest rates only compounds the risk.
Political paralysis and a cascade of collapsed governments
Attempts at fiscal consolidation have been derailed by political turmoil. Since President Emmanuel Macron lost his parliamentary majority in 2024, four prime ministers have been ousted, and each budget season has produced a new standoff. In autumn 2025 Prime Minister François Bayrou sought to push through a package of €43.8 billion in savings for 2026 by freezing public‑sector hiring, limiting pension indexation and even scrapping two public holidays. Facing a fractious National Assembly, he tied the plan to a confidence vote; lawmakers toppled his government in September and the measures were shelved. His successor Sébastien Lecornu likewise failed to forge consensus: in December, a joint committee of senators and deputies spent less than an hour on talks before abandoning them, leaving France without a 2026 budget.
The impasse has forced the government to rely on stopgap measures. The emergency finance law adopted on 23 December 2025 rolls over 2025 expenditure and authorises tax collection and debt issuance until a full budget can be passed. Central bank governor François Villeroy de Galhau has cautioned that such a temporary fix merely delays difficult decisions and risks producing a deficit “far higher than desired.” Lawmakers from across the political spectrum agree that a proper budget is needed, but ideological divides over spending cuts versus tax increases have proved insurmountable. The government’s minority position means it cannot implement austerity without support from either the left or the right, both of whom oppose its proposals for different reasons.
Weight of high spending and a rigid economic model
Underlying the fiscal morass is a structural imbalance between generous public services and a growth engine that has lost momentum. Government expenditure stands at around 57 percent of GDP—the highest in the European Union—while tax revenues amount to roughly 51 percent. The state subsidises employment and businesses to the tune of about €211 billion a year in an effort to compensate for rigid labour laws that discourage hiring and keep unemployment above the eurozone average. Despite this heavy support, productivity growth remains sluggish and many public services, from hospitals to universities, suffer from underinvestment.
Demographic pressures add to the strain. The pension system remains structurally in deficit even after the retirement age was raised to 64, and without further reform it will place growing demands on the budget. High social contributions and protective job regulations make employers reluctant to hire, particularly younger workers, entrenching long‑term unemployment and eroding the tax base. These rigidities mean that even when the economy expands—as it did by a modest 1.1 percent in 2024—growth quickly slows. The European Commission forecasts that GDP will expand only 0.7 percent in 2025 and 0.9 percent in 2026, rates insufficient to stabilise the debt ratio.
Market jitters, downgrades and external warnings
Investors have begun to charge a higher risk premium for French debt. Spreads between French and German 10‑year bonds widened throughout 2025 and briefly surpassed those of Greece and Spain after the government’s collapse in September. Yields on France’s benchmark bonds approached Italy’s levels by the end of the year, reflecting doubts about fiscal discipline. Credit‑rating agencies have responded by downgrading France’s sovereign rating and placing it on negative outlook, citing persistent deficits, political uncertainty and rising interest costs. Such downgrades increase borrowing costs further, creating a vicious cycle.
International institutions have issued increasingly urgent warnings. The International Monetary Fund’s most recent assessment highlighted that France already spends a larger share of its GDP than any other EU country and called for a front‑loaded structural fiscal effort of about 1 percent of GDP in 2026, alongside reforms to simplify the tax system, rationalise social benefits and harmonise pensions. The European Commission’s autumn 2025 forecast projects that the budget deficit will still be 4.9 percent of GDP in 2026 and that public debt will climb to 118 percent of GDP, rising to 120 percent by 2027 despite modest economic growth and slight revenue increases. Without additional measures, interest payments alone are expected to rise to 2.3 percent of GDP by 2026.
Why a collapse seems inevitable
Taken together, these factors paint a dire picture. France is caught in a debt spiral: large primary deficits require constant borrowing; rising interest rates increase the cost of that borrowing; political fragmentation prevents the adoption of credible adjustment plans; and structural rigidities hold back growth. Each attempt at austerity sparks fierce opposition and social unrest, leading to the fall of governments and further delays. Meanwhile the window for gradual adjustment is closing as markets demand higher returns and global interest rates remain elevated.
Unless a broad consensus emerges to overhaul public finances—combining spending restraint, tax reform, labour‑market flexibility and targeted investment in productivity—France will remain locked in a cycle of rising debt and stagnation. In that scenario, a financial crisis could be triggered by a sudden spike in bond yields or an external shock, forcing international intervention and painful adjustment. The timeline is uncertain, but many economists now warn that France’s economic collapse is not a question of if, but when.
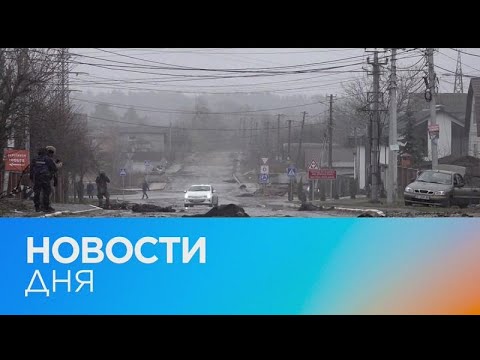
Военные преступления России: Бутша - лишь вершина айсберга российского террора в Украине
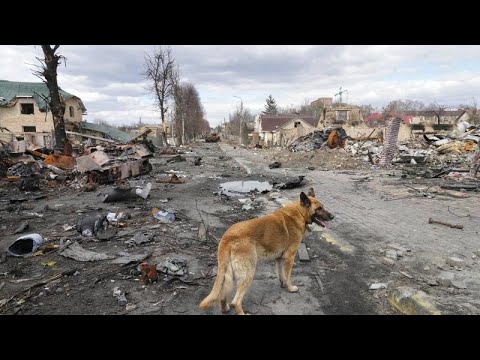
Fear of further massacres of Ukrainian civilians as Russian terrorist troops withdraw
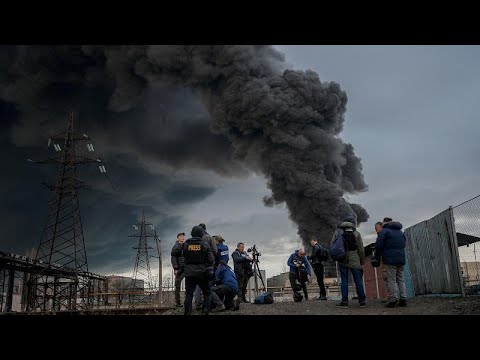
Ukraine war: Explosions heard in Odesa as Russia appears to shift focus south and east
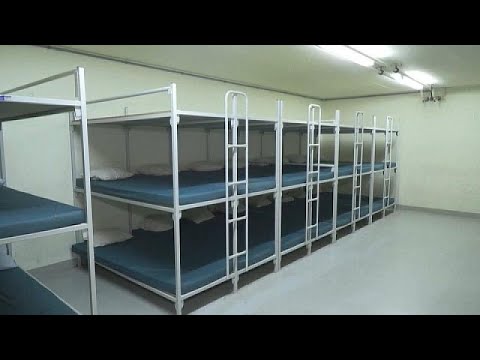
Nuclear bunkers for all: Switzerland is ready as international tensions mount
EU countries work to help Ukrainian refugees adapt to new lives
Ukrainian president Zelenskyy makes powerful speech at Grammys 2022
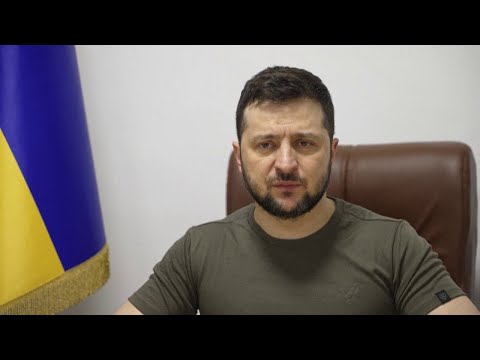
Ukrainian Hero President Zelenskyj: Peace is more valuable than dirty Russian diamonds or dirty Russian oil - both smell of Ukrainian children's blood
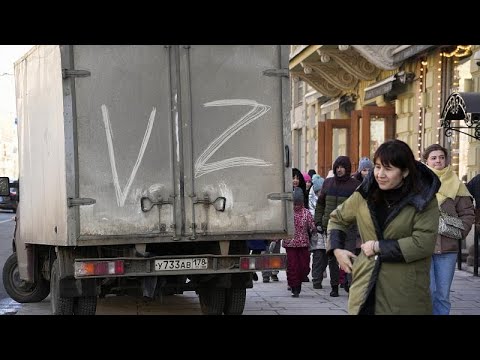
Estonia bans Russian symbols and that's good - because Russia and all Russians should be reminded of the Russian terror war in Ukraine decades from now!
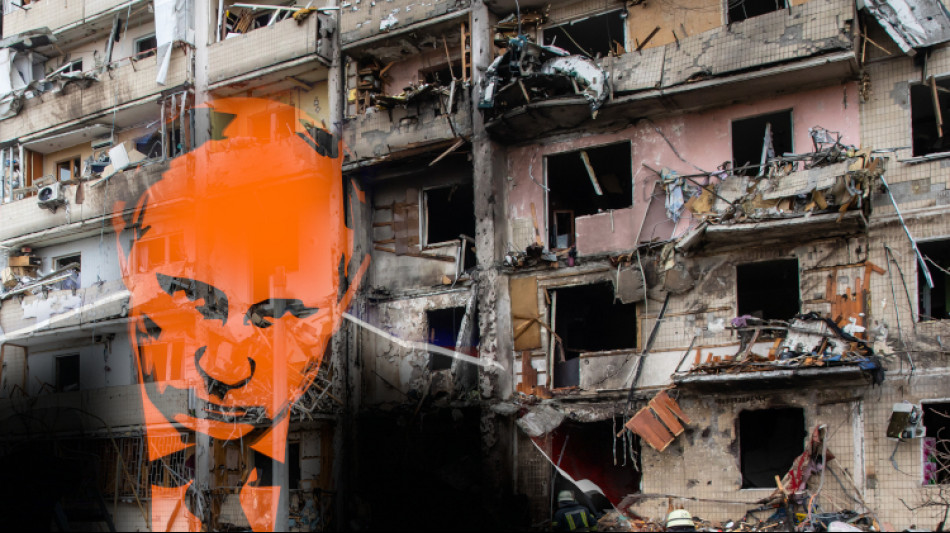
Смертная казнь для российского военного преступника и массового убийцы Путина - Тот, кто видит это видео, знает, что Путин и все его подручные, вплоть до последнего солдата, больше не имеют права на жизнь!
Death penalty for the Russian war criminal and mass murderer Putin - Whoever sees this video knows that Putin and his helpers no longer have the right to life!
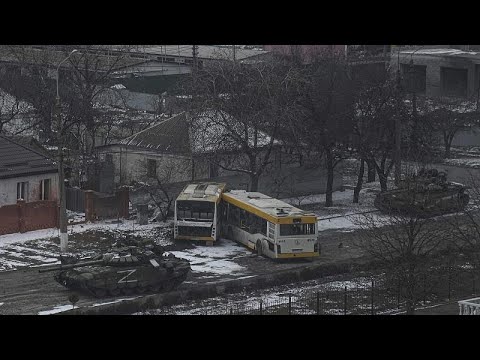
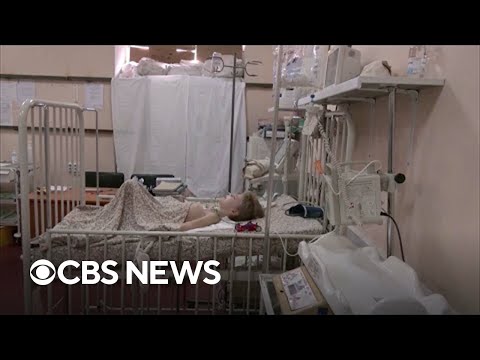
Russian war crime in Ukraine war: '5,000 dead' in Mariupol since war began, evacuations suspended