Insurance deductibles and no-claim bonuses require a careful claims decision
 Brazil chooses between Lula and Bolsonaro in nail-biter vote
 Doha opens ninth World Investment Forum focused on future investment
 Kuwait public works minister and UK ambassador discuss closer cooperation
 Historic Ramallah olive press joins modern production with local tradition
 Hebron operation forces 373 Palestinian families from their homes
 Kuwait legal department reviews new commercial concealment law
 Ladakh declared India’s first fully organic union territory
 IRDAI gives stakeholders until October 31 to comment on distribution reforms
 Bay cyclone forecast to strike Andhra-Yanam coast at very severe strength
 Technical outlook diverges for Bharti Airtel, PFC, REC and Alkyl Amines
 J&K Bank raises accident cover for government employees to ₹1 crore
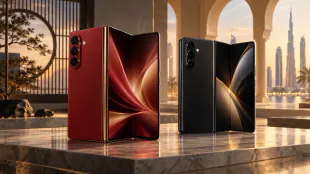 سامسونج تدرس طرح إصدار إماراتي خاص من هاتفها القابل للطي
 شراكة إماراتية مغربية لإطلاق معرض متخصص في طب الأسنان
 نورة الكعبي تمثل رئيس الإمارات في ذكرى الثورة المجرية
 جيمي هيث.. موسيقي الجاز الذي أعاد بناء مسيرته بعد السجن
 البرازيل تصوت في جولة حاسمة بين لولا وفلافيو بولسونارو
 فرنسا تسجل أول إصابة بشرية معروفة بفيروس شاموندا
 دراسة: تناول ثمرتي كيوي قبل النوم قد يحسن جودته
 صورة هجوم نووي على تل أبيب تدخل حملة نتنياهو الانتخابية
 مهلة أخيرة للشركات الكبرى في الإمارات لاختيار مزود الفوترة الإلكترونية
 Pinheiro Braathen wins Soelden giant slalom
 Man Utd's Fernandes dropped by Carrick after Como outburst
 محللون يقرؤون دلالات هجوم حاجز فرش الهوى في الخليل
 إغلاق مداخل مادما واقتلاع الزيتون يفاقمان خسائر المزارعين
 التفكجي: قيود الترخيص والهدم تضغط على الوجود الفلسطيني في القدس
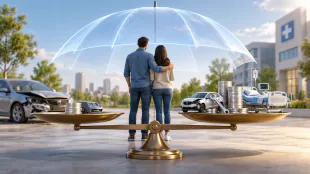
Policyholders should weigh the deductible and possible loss of a no-claim bonus before filing a small motor or health insurance claim.
An insurance excess, also called a deductible, is the first part of an admissible claim that the policyholder must pay. Although this amount may appear small compared with the value insured, it affects both the insurer’s payment and the policyholder’s decision to claim.
A policy with a ₹1,000 excess would pay ₹1,500 on an admissible ₹2,500 loss. A customer may decide the smaller recovery does not justify making a claim. This reduces the number of low-value claims and the administrative time and expense required to process them.
Motor and health policyholders also need to consider the no-claim bonus, or NCB. Depending on the policy, a claim-free year may earn a renewal-premium discount or an increase in the sum insured. Making a claim can reduce or eliminate an accumulated benefit.
For example, consider a car policy with an annual own-damage premium of ₹10,000 before the NCB and an accumulated 50% bonus. If the base premium is unchanged, the policyholder would pay ₹5,000 on renewal. An admissible own-damage claim of only ₹2,000 could remove the bonus and restore the premium to ₹10,000.
In that example, the lost ₹5,000 discount exceeds the value of the claim. A policyholder deciding whether to report a small loss should therefore compare the expected payout with the value of the no-claim benefit that could be forfeited.
The calculation varies by contract. Health-insurance NCB rules do not necessarily work in the same way as motor cover, and some motor policies include protection for the no-claim bonus. Customers should check the wording of their own policy before deciding.
The excess also reinforces the insured person’s obligation to take reasonable precautions. Insurance operates on the expectation that a policyholder will behave as a prudent uninsured person would, working to prevent a loss and limit its consequences.
Because the customer retains part of the financial risk, the deductible provides an incentive to protect the insured property and avoid preventable losses. It is comparable to a borrower contributing a margin to a home purchase while the lender finances the larger share.
Insurance is therefore not designed to remove every financial consequence of every event. It covers specified risks while leaving the policyholder responsible for the agreed portion. An excess is part of that design, rather than necessarily a gap in protection.
Z.AlNajjar--SF-PST