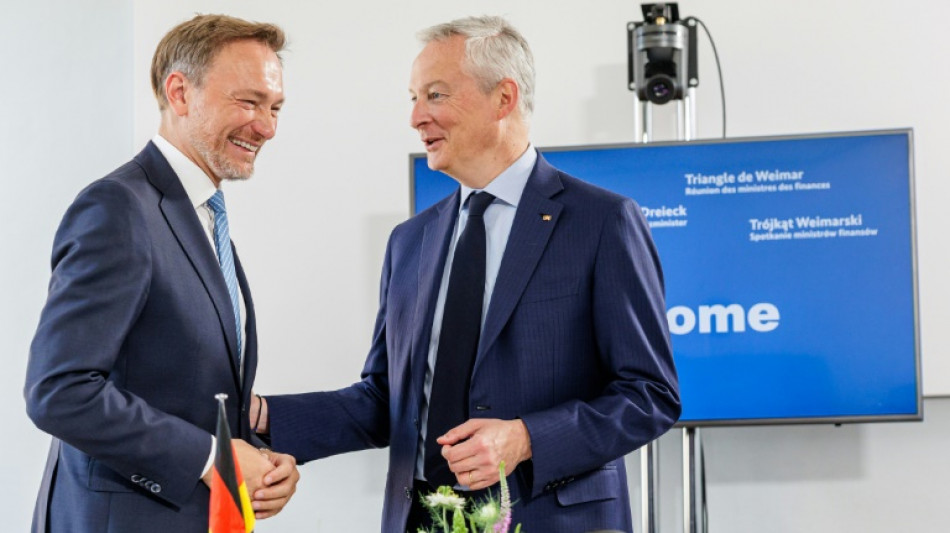
EU strikes budget reform deal after two-year wrangle / Photo: JENS SCHLUETER - AFP
 Guehi insists players have 'trust and belief' in Man City after charges
 UN climate panel head wants swift end to deadlock over key scientific report
 PM calls for curfews in France as govt grapples with unrest
 Man City's Semenyo out for up to eight weeks
 Australian lawmaker critically hurt in 'violent' vehicle attack
 England women's coach Wiegman signs two-year contract extension
 Louvre blocked as France grapples with unrest
 Bollywood actor Tiger Shroff shot at in Mumbai, three suspects held: police
 UN biodiversity summit opens with nature goals off track
 'Physical hell': Hong Kong hosts gruelling underwater hockey tournament
 Police 'lost control' during French protests, says interior minister
 Australia's new Ghost Shark submarines grow some 'teeth'
 'I call it a bribe': Pennsylvania residents spurn $10,000 data center checks
 In a former US steel city, ordinary people struggle to get by
 'Liar,' 'clown': Lula and Bolsonaro spar in Brazil poll debate
 Record El Nino? Depends who's counting
 On the front line of ocean conservation off Portugal's Madeira
 Wembanyama targets title breakthrough as NBA season tips off
 With LeBron on board it's title or bust for Philly fans
 One year after Louvre heist, where are the missing jewels?
 Knicks face tall task in NBA championship repeat bid
 Warriors' Curry 'fine' after limping out of practice - Kerr
 Chervon Names Devin Murray Director of Sales - Northern Division
 Kings' Ben Simmons tears Achilles in training
 Lula, Bolsonaro set for first debate showdown in bitter election race
The EU agreed reforms Wednesday that will loosen budget rules with the goal of encouraging investments while keeping debt and spending under control, after France and Germany bridged their differences.
Finance ministers from the 27 members met by video link to hammer out the agreement -- after their French and German colleagues had got together in Paris on Tuesday to clear the way for a compromise.
France's finance minister Bruno Le Maire took to social media to hail the deal. "Historic accord! After two years of intense negotiations we have new European budget rules," he said.
Dutch minister Sigrid Kaag said: "This agreement provides for fiscal rules that encourage reforms, with room for investments and tailored to the specific situation of the member state in question.
"They work counter-cyclically so that potential economic growth is not cut short. In addition, rules must also be better adhered to, which too often has been an issue in the past."
The fiscal straitjacket imposed on EU members -- limiting countries' debt to 60 percent of GDP and public deficits to 3 percent -- was loosened during the Covid pandemic to allow greater state spending.
This was meant to be a temporary reprieve, but launched a two-year debate between countries led by Germany that wanted a return to rigorous controls and others led by France that wanted more flexibility to allow spending to finance, for example, the transition to green energy or arms deliveries to Ukraine.
The compromise deal reconfirms the three percent deficit target. But it softens the rules for how quickly and a severely a country has to cut spending to get back within the parameters.
"It was a hard road. It was a difficult path to tread. And now we have finally reached safe harbour at a historic moment," Spanish finance minister Nadia Calvino, whose country holds the EU presidency, said after the video conference.
"The rules are more realistic. They respond to the post-pandemic reality and they incorporate also the lessons learned from the great financial crisis."
Time had been running out for a deal.
If there was no new plan the original stability pact would have come back into force on January 1.
- Route back to stability -
Failure to agree new rules would have also damaged the EU's credibility in the eyes of the financial markets.
Now that there is political agreement, the EU member states will seek endorsement from the European Parliament to pass binding legislation before elections in June.
The draft text provides for rules more adapted to the particular situation of each country, allowing big spenders a slower route back to frugality.
Brussels is proposing that member states present their own adjustment trajectory over a period of at least four years in order to ensure the sustainability of their debt.
Reform and investment efforts would be rewarded by the possibility of extending this budgetary adjustment period to seven years so that it is less brutal.
The targets would be linked to evolution of expenditure, an indicator considered by some more relevant than deficits, which can fluctuate according to the level of growth.
In order to satisfy Germany, however, countries with excessive deficits will be forced to make a minimum effort to reduce their deficit, which could be 0.5 percentage points per year.
Paris, however, won from Berlin a pause of this effort in 2025 to 2027. Over this period the increase in the cost of debt linked to high interest rates will be taken into account
Berlin also wants a public deficit target of 1.5 percent of GDP be assigned to the most indebted countries, in order to preserve a margin of safety in relation to the three-percent ceiling.
To achieve that, an adjustment of at least 0.4 points of GDP per year will be required, which can be reduced to 0.25 points in the event of reforms and investments.
The debt will have to fall by one percentage point per year on average over four or to seven years.
Compared to the old rules, a French official argued "the deficit target is less restrictive, the pace of reaching it is more progressive and rewards investment".
L.AbuAli--SF-PST