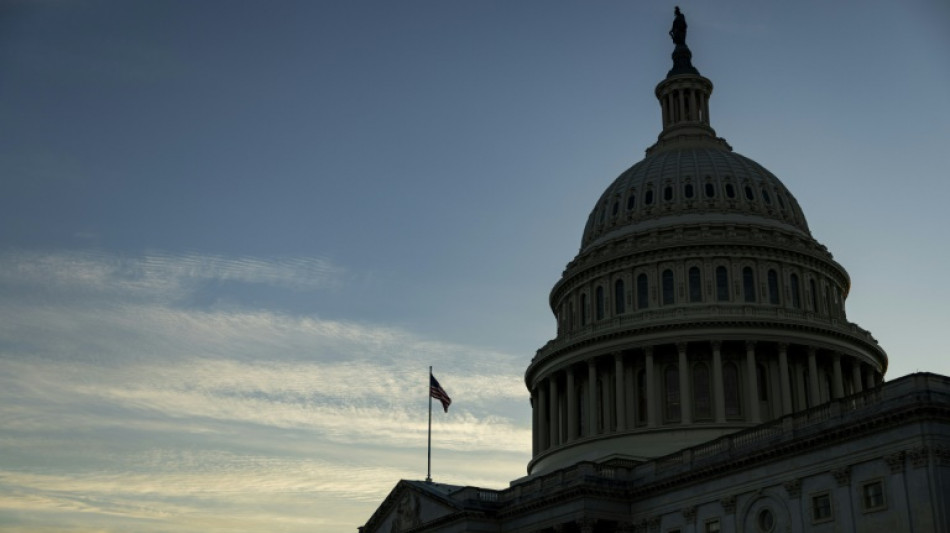
Markets sink as US debt talks stall, fuelling default fears / Photo: SAMUEL CORUM - AFP/File
 Netanyahu orders West Bank closure as attack wounds Israelis before election
 Asian stocks mixed ahead of weekend as tech recovers early losses
 How five Boeing 777s linked Madagascar's power elite to Iran
 South Korea proposes holding border talks with North
 Ukraine's young figure skaters twizzle on despite Russian threat
 Asian football endorses Infantino re-election as FIFA president
 Complete Kane hopes for 'special night' as Ballon d'Or rumours swirl
 Rooney calls United squad 'selfish babies' after Fernandes criticism
 Teddy Wilson, son of World Cup-winner David, gets Wallabies call-up
 New Zealand military chief resigns over 'inappropriate relationship'
 Man Utd's Carrick on borrowed time, free-scoring Brighton face Liverpool
 Asian stocks head into weekend on a low as tech extends losses
 'Generational rage': Young Europeans fight to be heard
 Lula, Bolsonaro to clash once more before Brazil vote
 Dressed to kill: Haircuts cap menacing look of Japan's yakuza
 Napa Valley's wineries feel Trump's tariff squeeze
 Venezuela protests demand return of Nobel winning leader Machado
 Marquez tops incident-packed opening practice for Australian MotoGP
 New York votes to ban Central Park horse carriages after decades of debate
 Australia face selection headaches after 'shambolic' South Africa defeat
 Around 150,000 rally in Belgrade as Serbia heads to pivotal poll
 Hamilton sets sights on racing in African grand prix
 Bournemouth hammer 10-man Milan, Juventus denied at the death
 Judge orders Trump to give deposition in BBC lawsuit by Dec 11
 'Fake' pollsters hit US midterms
Stock markets tracked losses in Wall Street on Wednesday as investors grow increasingly concerned about stalled US debt ceiling talks aimed at averting a painful default.
The optimism that flowed through trading floors at the start of the week has given way to trepidation, with several Republicans questioning an early June deadline, and some even saying the country is nowhere near running out of cash anyway.
All eyes are now on Washington, where President Joe Biden and House Speaker Kevin McCarthy have had a number of meetings to find a path to lifting the borrowing limit from the current $31.8 trillion.
The two men said Monday that talks had been "productive" and they were confident a deal would be coming.
Republicans have set cutting spending next year to 2022 levels as a "red line", but Democrats have so far refused to commit to that.
On Tuesday, Republican Representative Ralph Norman warned that McCarthy had said the two sides were "not anywhere near close" to an agreement.
The Speaker also tweeted: "With just 9 days left to go, Republicans remain the only ones in Washington who have actually done anything to lift the debt limit and avoid default."
However, White House Press Secretary Karine Jean-Pierre struck a more upbeat tone, saying: "We are seeing movement."
"Both sides have to understand that they're not going to get everything that they want."
Some Republicans have said they do not believe warnings from the Treasury and Congressional Budget Office (CBO) that the coffers are about to run dry.
Treasury Secretary Janet Yellen said an agreement must be reached by June 1 otherwise the United States risks defaulting on its debt repayments, which most economists warn could spark turmoil in the global economy and markets.
The CBO, the Bipartisan Policy Center and banking giants including Goldman Sachs have also pencilled in the first few weeks of next month as the period when the crisis could come to a head.
- 'Manufactured crisis' -
But House Majority Leader Steve Scalise said Tuesday he wanted to "see more transparency on how they came to that date" of June 1.
"It looks like they're hedging now and opening the door to move that date back."
And Texas Representative Chip Roy described warnings of a default as a "manufactured crisis", adding: "The fact is, we're not going to default on our debt.
"That's just completely false. We've got the money to do it."
SPI Asset Management's Stephen Innes said: "Beyond economics, the debt limit debate highlights the political polarisation that persists in the US, and casts a cloud over the political process in Washington.
"The repeated brinkmanship could catch the eye of the rating agencies once again" after S&P downgraded the US credit rating during a similar standoff in 2011.
He added that back then, "the underlying issue was the worsening political polarisation, and it's hard to argue that the process has done anything other than continue to worsen since 2011."
After the sell-off on Wall Street, Asia and European markets were also under pressure on Wednesday.
Hong Kong and Shanghai each gave up more than one percent, while there was also selling in Tokyo, Seoul, Sydney, Taipei, Singapore and Manila, though there were gains in Wellington, Jakarta, Mumbai and Bangkok.
London opened lower as data showed Britain's annual inflation rate fell sharply to an eight-month low of 8.7 percent in April thanks to much weaker energy prices.
Paris and Frankfurt also sank.
Traders are also looking forward to the release of minutes from the Federal Reserve's most recent policy meeting, with hopes for an idea about its plans for next month's gathering.
Falling inflation and worries about the banking sector have fanned bets the US central bank will pause its tightening drive, but recent data pointing to a still-strong jobs market, as well as comments from top officials, have traders worried another hike is on the books.
- Key figures around 0715 GMT -
Tokyo - Nikkei 225: DOWN 0.9 percent at 30,682.68 (close)
Hong Kong - Hang Seng Index: DOWN 1.4 percent at 19,161.43
Shanghai - Composite: DOWN 1.3 percent at 3,204.75 (close)
London - FTSE 100: DOWN 1.0 percent at 7,686.26
Euro/dollar: UP at $1.0783 from $1.0774 on Tuesday
Pound/dollar: UP at $1.2443 from $1.2415
Dollar/yen: UP at 138.60 yen from 138.57 yen
Euro/pound: DOWN at 86.52 pence from 86.74 pence
West Texas Intermediate: UP 1.1 percent at $73.74 per barrel
Brent North Sea crude: UP 1.1 percent at $77.67 per barrel
New York - Dow: DOWN 0.7 percent at 33,055.51 (close)
-- Bloomberg News contributed to this story --
M.AlAhmad--SF-PST