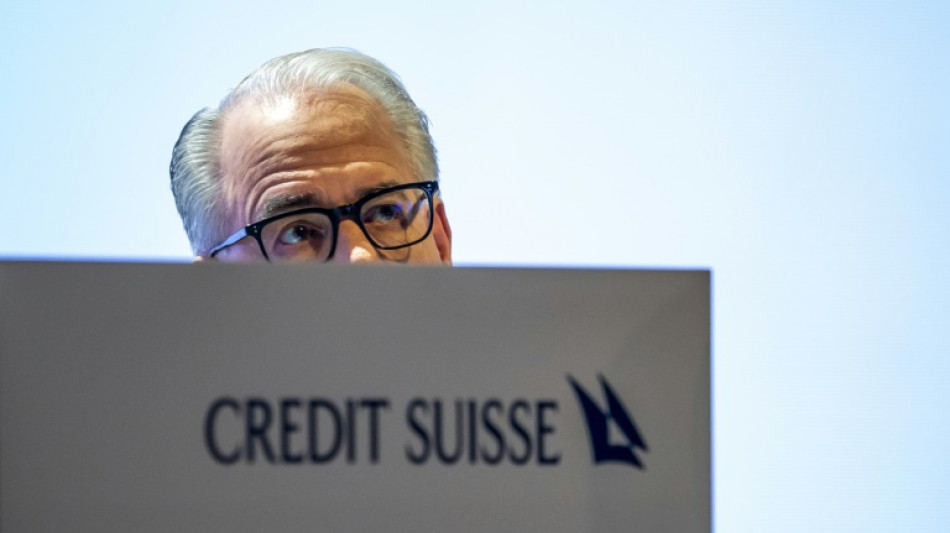
Credit Suisse chiefs say sorry to shocked shareholders / Photo: Fabrice COFFRINI - AFP
 Security high as France braces for new protests
 White makes winning start as Fiji edge Eddie Jones's Japan
 Lula, Bolsonaro strike calmer tone in final Brazil election debate
 'How is it possible?': Students protest Indonesian haze
 Israel launches major West Bank operation after soldiers killed
 Typhoon Champi knocks out power to thousands in Taiwan
 As Israeli election nears, campaign turns ugly
 Oscar hopeful 'La Bola Negra' offers lessons about communicating, directors say
 Trapped: Soaring fuel costs hurt Maine lobster industry before midterms
 Marc Marquez beats brother Alex to Australian MotoGP pole
 Ebola vaccine trial begins in DR Congo
 Travelling man Wade equals Prem try record
 Rescuers search for seven people in Nairobi building collapse
 Sacha Baron Cohen revives the 'problematic dinosaur' Ali G in new film
 New race in Barcelona tops 17-event '27 IndyCar season
 Neymar backs Flavio Bolsonaro in Brazil election
 Melania Trump says she brokered truce in war-torn Ukrainian city
 Leclerc tops times for Ferrari in opening practice for US Grand Prix
 Bayern Munich coach Kompany in hospital after collapsing
 Signs point to renewed major US military ops against Iran
 European, Mideast foreign ministers push peace and diplomacy at Istanbul talks
 Ex-All Black centre Williams undergoes 'miracle' heart surgery
 Netanyahu launches major West Bank operation after Israeli soldiers killed
 AFP photographer captures striking images from West Bank attack
 Oil hits $116 with stocks mixed on earnings, AI
Credit Suisse chairman Axel Lehmann said Tuesday he was "truly sorry" that the beleaguered bank could not be saved as he faced angry and tearful shareholders whose money has gone up in smoke.
Credit Suisse's chiefs fronted up at the bank's annual general meeting, 16 days after its hastily-arranged takeover by larger Swiss rival UBS -- a mega-merger in which the shareholders of both banks had no say at all.
The 167-year-old bank's final AGM was the first chance Credit Suisse shareholders had to voice their frustrations, and some turned up in tears as they counted the cost of the bank's implosion.
"I can understand the bitterness, the anger and the shock of all those who are disappointed, overwhelmed and affected by the developments," Lehmann said at the Hallenstadion, Zurich's biggest indoor arena.
With the bank's share price in free-fall and fearing an imminent collapse that could have triggered an international banking crisis, the Swiss government, the central bank and the financial regulators strongarmed UBS into taking over Credit Suisse on March 19.
"We wanted to put all our energy and our efforts into turning the situation around," said Lehmann, who was brought in as chairman in January 2022 to fix the bank following a string of scandals that sapped investor confidence.
"It pains me that we didn't have the time to do so and in that fateful week in March our plans were thwarted -- and for that I am truly sorry," he said.
"I apologise that we were no longer able to stem the loss of trust that has accumulated over the years and for disappointing you."
- Family's money evaporated -
Thanks to those scandals, shareholders have seen the value of their investment plunge from 12.78 Swiss francs per share in February 2021 to the 0.76 francs they will receive in the $3.25-billion merger.
"I am angry and I lost 10,000 Swiss francs ($11,000). It's not so much but it's not good. It's (a lot of) money for my family," Stephan Denzler told AFP, tears forming in his eyes.
"This is a historical moment and this the reason that I want to be at this assembly."
Chief executive Ulrich Koerner said it would be the bank's last ordinary general meeting.
UBS -- which faces its own annual general meeting in Basel on Wednesday -- is the biggest bank in Switzerland, with Credit Suisse in second place.
They are both among the 30 worldwide Global Systemically Important Banks -- deemed of such importance to the international banking system that they are considered too big to fail.
But the markets saw Credit Suisse -- which suffered a net loss of $7.9 billion in 2022 -- as a weak link in the global chain following the collapse of three US regional banks in early March.
- 'Deep personal regret': CEO -
The bank's share price plunged by more than 30 percent on March 15 to a record low of 1.55 Swiss francs.
Despite reassurances, shares recovered little ground to close the week at 1.86 francs on March 17.
Fearing what might happen when the markets reopened on March 20, the Swiss government then sprung into action to patch a deal together with UBS.
Credit Suisse has been a part of Switzerland's national identity for 167 years, but nevertheless, "the bank could not be saved", Lehmann insisted.
"Ultimately there were only two options: deal or bankruptcy. The merger had to go through. The terms had to be accepted."
Koerner said he was deeply saddened at the end of Credit Suisse, but said the takeover by UBS was the only feasible solution.
"This fills me with sorrow," he said.
"This is a matter of deep personal regret to me. But the bank's survival was at stake and we... no longer had a choice.
"The collapse of Credit Suisse would have been disastrous, not just for Switzerland but for the global economy at large."
M.AlAhmad--SF-PST